An Indefinite Freeze Requires Answers
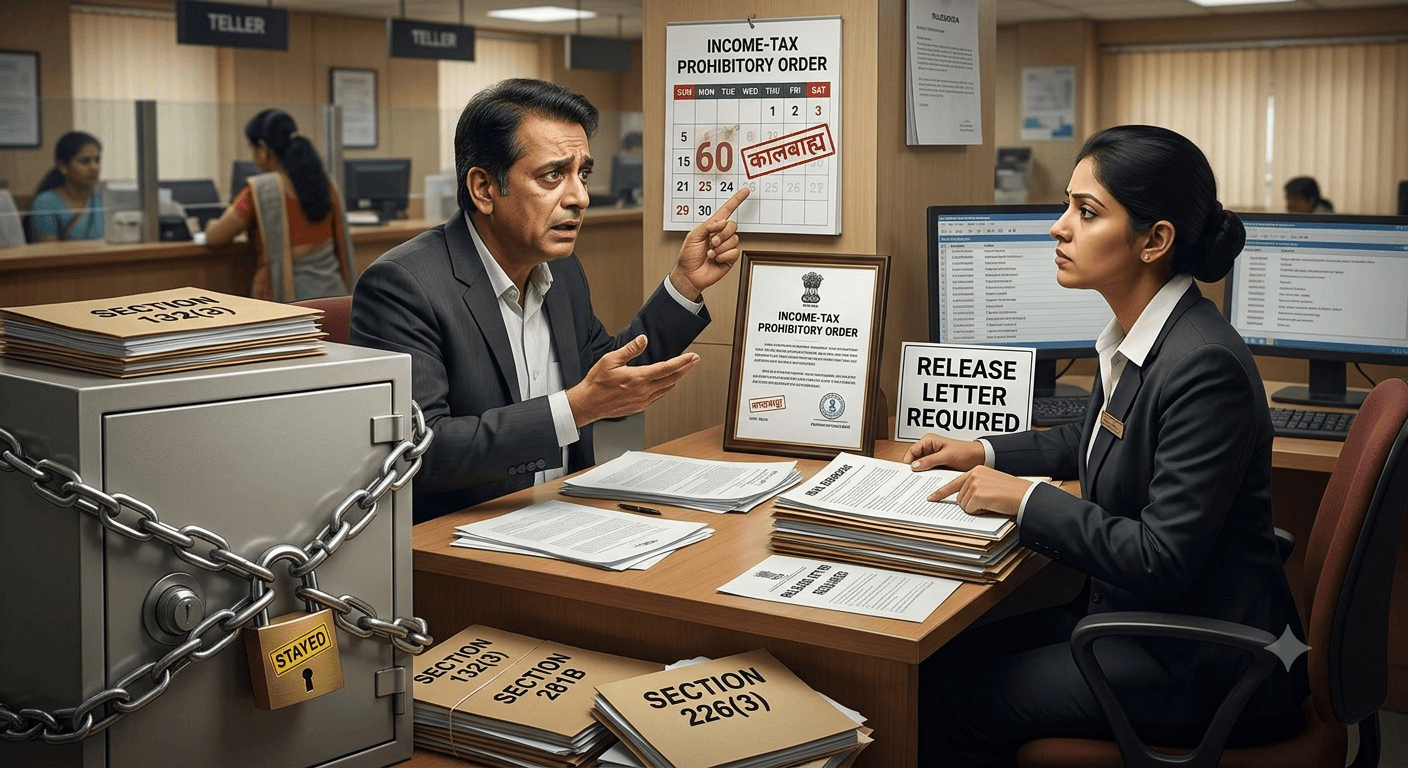
An Income-tax prohibitory order freezes a bank account. Sixty days expire, but the bank demands a departmental release letter. It asserts that an order exists without supplying its copy. The Income-tax office asks the taxpayer to produce that order before confirming its lapse.
This deadlock does not create legal authority for continuing the restriction. The bank must identify the subsisting basis for denying account operations. Crucially, a search restraint, provisional attachment and recovery notice are different instruments with different consequences.
Section 132(3): Search Restraint Under the 1961 Act
Section 132(3) authorises restraint where seizure of specified documents or assets is impracticable for the prescribed reasons. The person possessing or controlling them may be prohibited from dealing with them without prior permission. Such restraint does not itself constitute seizure.
Section 132(8A) limits its duration. Its operative words are:
“shall not be in force for a period exceeding sixty days from the date of the order”.
The Department’s published guidance confirms 60 days from the order’s date. Pending investigation does not, by itself, extend this restraint.
Section 247(4)(b): Corresponding Provision in the 2025 Act
Under the Income-tax Act, 2025, section 247(4)(b)(i) provides the corresponding restraint mechanism, expressly covering bank accounts and bank lockers.
Section 247(4)(b)(ii) states:
“such order shall not remain in force for a period exceeding sixty days from the date of the order”.
Section 247(4)(b)(iii) distinguishes this restraint from deemed seizure. Older orders require examination under the applicable enactment and transitional provisions.
Statutory expiry does not depend on express revocation. A release letter may confirm expiry; its absence does not itself extend the original order.
Section 281B and Section 500: Provisional Attachment
Section 281B of the 1961 Act empowers the Assessing Officer, during specified pending assessment, reassessment or qualifying penalty proceedings, to provisionally attach property to protect revenue. It requires a written order and previous approval of the prescribed authority.
Under section 281B(2), the attachment ordinarily expires after six months. Extensions require action by the specified authority and recorded reasons. The total extension period cannot exceed two years or sixty days after the assessment or reassessment order, whichever is later.
The corresponding provision is section 500 of the 2025 Act. Sections 500(1), 500(2) and 500(3) respectively address attachment, the initial six-month duration and permitted extensions.
An expired section 132(3) order does not automatically become a section 281B attachment. A separate attachment must satisfy its own statutory conditions.
Section 226(3) and Section 416(5): Recovery Notices
Section 226(3) of the 1961 Act is a recovery mechanism, commonly described as a garnishee notice. The Assessing Officer or Tax Recovery Officer may require a person holding, or owing, money for the assessee to pay towards tax arrears.
Its corresponding provision is section 416(5) of the 2025 Act, particularly section 416(5)(a).
Neither the search restraint’s 60-day limit nor provisional attachment’s six-month limit applies merely because the recipient is a bank. A recovery notice requires separate examination of its terms, the recoverable demand and any amendment, revocation or operative stay.
Significantly, section 226(3)(iii) and section 416(5)(d) require a copy of the notice to be forwarded to the assessee and relevant joint holders.
The Bank Cannot Hide Behind a Generic “Income-tax Freeze”
The bank should identify the section, order date, reference, issuing authority, amount and operative scope. If relying on an extended attachment, it should identify the extension supporting its present operation.
The existence of a statutory power is not proof that a valid order currently exists. Equally, an internal requirement for a release letter cannot replace missing legal authority.
Withholding the document while demanding that the customer obtain departmental clearance is an avoidable administrative failure. If disclosure is considered restricted, the bank should explain why and send the document directly to the Department for verification.
Recordkeeping difficulties do not create a fresh restraint.
Vinayan K: Relief and Its Proper Scope
In Vinayan K v. Income Tax Department, W.P.(C) 23437/2026, decided on 23 July 2026, the Kerala High Court permitted account operation after departmental counsel confirmed that no prohibitory order subsisted. Counsel’s statement did not cause statutory expiry, although relief rested on that recorded position.
The taxpayer should demand a written decision, escalate through the bank’s grievance mechanism and consider appropriate High Court relief.
The bank’s responsibility is to establish the operative basis for its restriction—not indefinitely preserve an expired PO because no release letter arrived. Conversely, a genuine recovery notice or valid attachment must be addressed under its own provisions.
By
CA Vijayakumar Shetty
Chartered Accountant | Mangalore
+91 98450 82430